Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Section 87A rebate may cover eligible short-term capital-gains tax under the earlier new-regime statutory framework.
    Make-available requirement limits treaty taxation of management and support fees unless recipients gain independently usable technical capability.
    October 5, 2026   Notes Money Laundering
    Pre-cognizance hearings under BNSS are mandatory for PMLA complaints when the cognizance stage is governed by BNSS.
    Fiscal transparency requires partner-specific treaty analysis for UK partnership income, preventing automatic FTS treatment of legal services.
    Input tax credit conditions require actual tax payment, but supplier default alone cannot justify mechanical credit reversal.
    Input tax credit conditions survive constitutional challenge, while retrospective supplier-cancellation demands require specific fraud findings and su...
    GST registration restoration for return non-filing requires pending returns and statutory dues, allowing business operations to resume conditionally.
    Electronic Cash Ledger Credits Do Not End Delayed GST Interest Until Debited Against Return Liability
    Recurring-issue exception to GST appeal thresholds requires genuine wider implications; absent proof, the departmental appeal is not maintainable.
    Judicial discipline requires consistent reassessment treatment where identical facts were decided for the same taxpayer in the preceding assessment ye...
    Limitation for Section 153C notices is measured from the assessment year in which satisfaction is recorded, excluding stale assessment years.
    Section 153C limitation invalidates a notice where the relevant assessment year falls outside the statutory look-back period.
    Revised Form-3 payment deadlines cannot require impossible compliance, preserving settlement closure after prompt payment under Vivad se Vishwas.
    Extended-period reassessment and digital evidence require statutory nexus and independent corroboration before tax additions can stand.
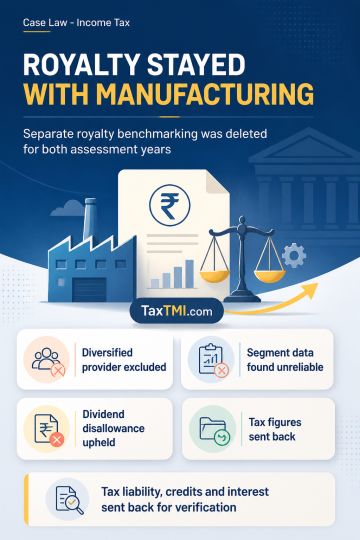
    TNMM aggregation of royalty with manufacturing precludes separate benchmarking, while non-comparable diversified service providers require exclusion.
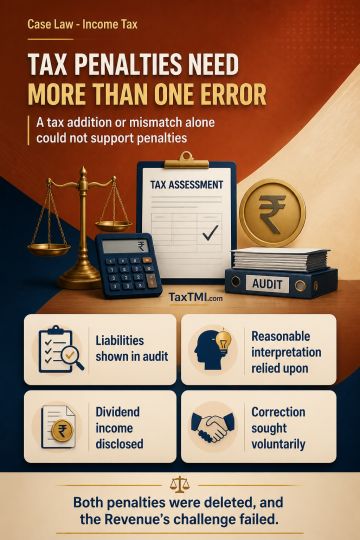
    Penalty for inaccurate particulars requires more than a Section 43B addition or a disclosed foreign-dividend reporting mismatch.
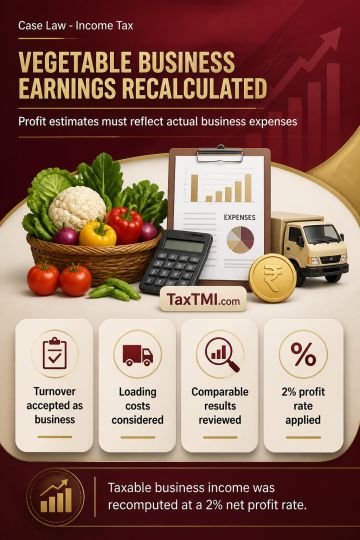
    Net profit estimation in vegetable commission business requires expense analysis, leading to recomputation of taxable business income.
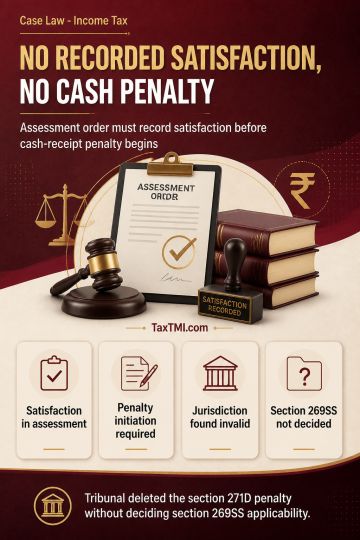
    Recording satisfaction in assessment proceedings is essential before cash-receipt penalties can be initiated; absent satisfaction, penalty fails.
    Search-related reassessment procedure displaces ordinary scrutiny assessment and invalidates regular assessments made after a search operation.
    Section 50C excludes unregistered contractual rights to seek land conveyance, preventing deemed-value recomputation of long-term capital gains.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Entry 34 of List II permits State legislation regulating or...

Betting on skill-based games remains within State legislative power when money is staked on uncertain outcomes.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Indian Laws September 25, 2026 Notes
Entry 34 of List II permits State legislation regulating or prohibiting betting on uncertain outcomes, including outcomes of predominantly skill-based games. The constitutional distinction is between the skill game itself and a wager placed on its uncertain result: a stake, uncertainty and expectation of gain bring the activity within betting and gambling, regardless of the game's skill classification. Genuine participation fees for skill competitions may remain distinct from outcome-linked stakes, requiring examination of the payment's function and the event's structure. Statutory exemptions for wagering on games of skill are matters of legislative policy and may be withdrawn. Online money-gaming restrictions may additionally rely on public order only where a real and proximate connection to community-wide disruption is established. Betting and gambling, as res extra commercium, does not attract proportionality review based on a claimed right to conduct that enterprise.

Topics

Acts Income Tax