Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
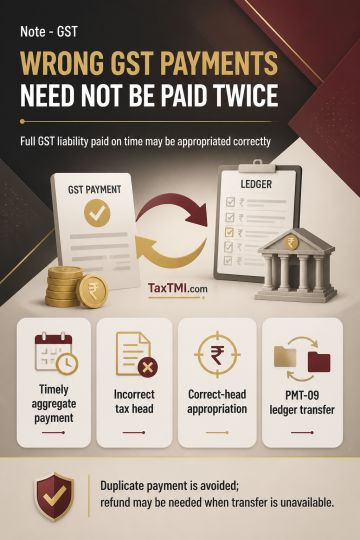
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931