Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
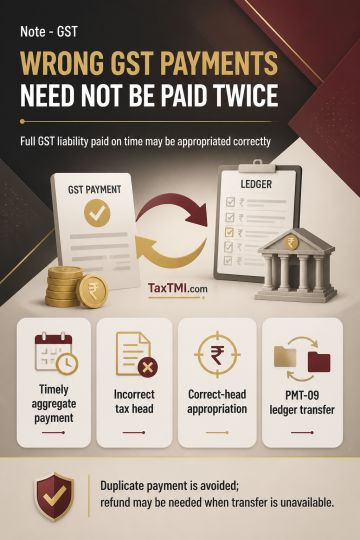
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913