Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
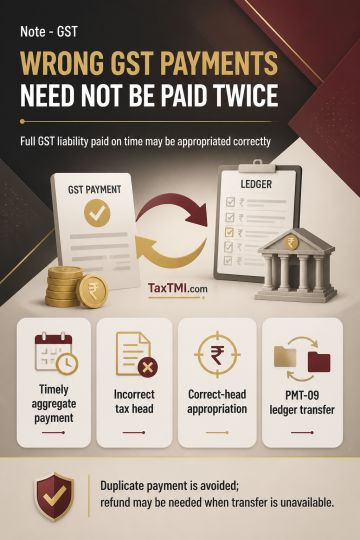
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915