Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
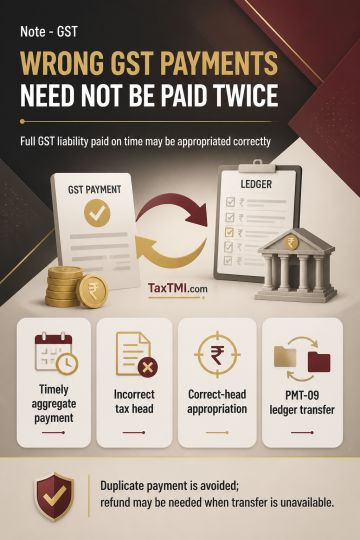
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Wrong-head GST remittances, where a taxpayer timely pays the full aggregate liability but selects an incorrect tax head, are distinct from a later correction of a supply's inter-State or intra-State character. Sections 19 of the IGST Act and 77 of the CGST Act, with Rule 89(1A), address classification errors and the related refund framework, not a pure allocation error. An identifiable wrong-head payment may be appropriated against the correct CGST and SGST liabilities rather than requiring duplicate payment followed by refund. Where funds remain in the electronic cash ledger, Section 49(10) and Rule 87(13) permit inter-head transfer through FORM GST PMT-09; refund may be procedurally necessary if transfer is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915