Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Section 153C jurisdiction requires timely deemed search and assessee-specific satisfaction material; otherwise reassessment must use the proper statut...
Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Page of 4915
Press 'Enter' after typing page number.
1161 to 1180 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
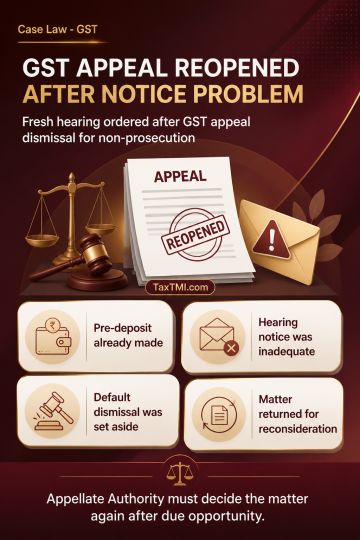
Dismissal of a duly constituted GST first appeal for non-prosecution, despite pre-deposit and alleged inadequate notice of hearing, should not leave the appellant remediless or compel a second appeal. Statutory procedure permits the Appellate Tribunal to dismiss an appeal for default and set aside that dismissal. High Court set aside the dismissal where there was no apparent reason for the appellant to abandon its appeal after making the pre-deposit, and remanded the matter to the Appellate Authority for fresh adjudication after due opportunity of hearing.
Dismissal of a duly constituted GST first appeal for non-prosecution, despite pre-deposit and alleged inadequate notice of hearing, should not leave the appellant remediless or compel a second appeal. Statutory procedure permits the Appellate Tribunal to dismiss an appeal for default and set aside that dismissal. High Court set aside the dismissal where there was no apparent reason for the appellant to abandon its appeal after making the pre-deposit, and remanded the matter to the Appellate Authority for fresh adjudication after due opportunity of hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915