Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
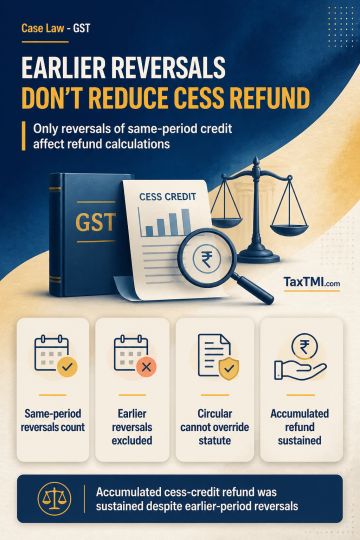
Rule 89(4) confines Net ITC for refund of unutilised cess credit on zero-rated supplies to credit actually availed during the relevant refund period. An ITC reversal recorded in GSTR-3B reduces Net ITC only where the reversed credit was availed in that same period; reversals relating to earlier tax periods do not affect the refund computation. Paragraph 43(c) of the departmental circular cannot require deduction of all reversals made during the refund period irrespective of the underlying credit period, as a circular cannot override or expand the statutory refund formula. The accumulated cess-credit refund was consequently sustained.
Rule 89(4) confines Net ITC for refund of unutilised cess credit on zero-rated supplies to credit actually availed during the relevant refund period. An ITC reversal recorded in GSTR-3B reduces Net ITC only where the reversed credit was availed in that same period; reversals relating to earlier tax periods do not affect the refund computation. Paragraph 43(c) of the departmental circular cannot require deduction of all reversals made during the refund period irrespective of the underlying credit period, as a circular cannot override or expand the statutory refund formula. The accumulated cess-credit refund was consequently sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913