Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
Page of 4915
Press 'Enter' after typing page number.
701 to 720 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
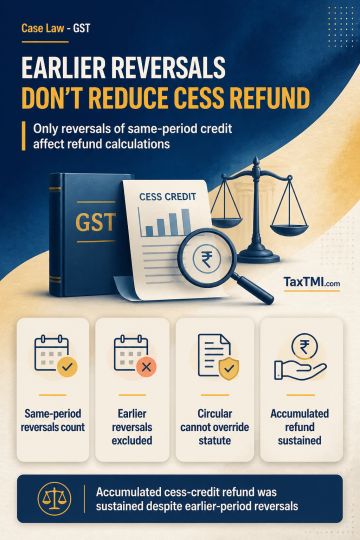
Rule 89(4) confines Net ITC for refund of unutilised cess credit on zero-rated supplies to credit actually availed during the relevant refund period. An ITC reversal recorded in GSTR-3B reduces Net ITC only where the reversed credit was availed in that same period; reversals relating to earlier tax periods do not affect the refund computation. Paragraph 43(c) of the departmental circular cannot require deduction of all reversals made during the refund period irrespective of the underlying credit period, as a circular cannot override or expand the statutory refund formula. The accumulated cess-credit refund was consequently sustained.
Rule 89(4) confines Net ITC for refund of unutilised cess credit on zero-rated supplies to credit actually availed during the relevant refund period. An ITC reversal recorded in GSTR-3B reduces Net ITC only where the reversed credit was availed in that same period; reversals relating to earlier tax periods do not affect the refund computation. Paragraph 43(c) of the departmental circular cannot require deduction of all reversals made during the refund period irrespective of the underlying credit period, as a circular cannot override or expand the statutory refund formula. The accumulated cess-credit refund was consequently sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915