Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
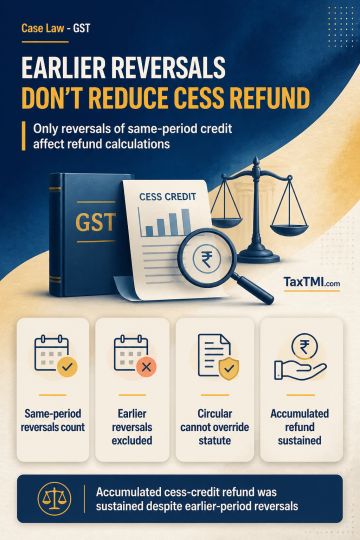
Rule 89(4) confines Net ITC for refund of unutilised cess credit on zero-rated supplies to credit actually availed during the relevant refund period. An ITC reversal recorded in GSTR-3B reduces Net ITC only where the reversed credit was availed in that same period; reversals relating to earlier tax periods do not affect the refund computation. Paragraph 43(c) of the departmental circular cannot require deduction of all reversals made during the refund period irrespective of the underlying credit period, as a circular cannot override or expand the statutory refund formula. The accumulated cess-credit refund was consequently sustained.
Rule 89(4) confines Net ITC for refund of unutilised cess credit on zero-rated supplies to credit actually availed during the relevant refund period. An ITC reversal recorded in GSTR-3B reduces Net ITC only where the reversed credit was availed in that same period; reversals relating to earlier tax periods do not affect the refund computation. Paragraph 43(c) of the departmental circular cannot require deduction of all reversals made during the refund period irrespective of the underlying credit period, as a circular cannot override or expand the statutory refund formula. The accumulated cess-credit refund was consequently sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915