Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Page of 4915
Press 'Enter' after typing page number.
681 to 700 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
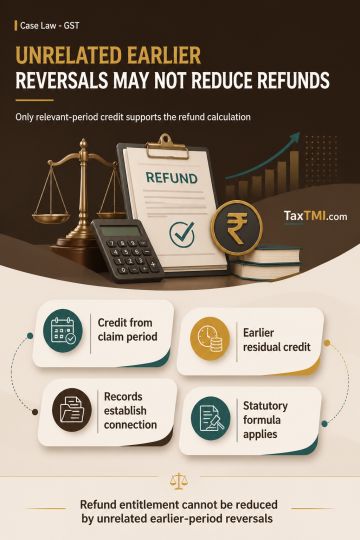
Net ITC for refund of unutilised Compensation Cess credit on zero-rated supplies is confined to input tax credit actually availed and attributable to the relevant refund period. A reversal recorded in that period need not reduce Net ITC where records establish that it relates to residual unutilised credit from earlier tax periods and was not included in the credit supporting the refund claim. Paragraph 43(c) of the departmental circular must operate consistently with the statutory refund formula and cannot require deduction of every reversal reported during the period, thereby curtailing a statutory refund entitlement.
Net ITC for refund of unutilised Compensation Cess credit on zero-rated supplies is confined to input tax credit actually availed and attributable to the relevant refund period. A reversal recorded in that period need not reduce Net ITC where records establish that it relates to residual unutilised credit from earlier tax periods and was not included in the credit supporting the refund claim. Paragraph 43(c) of the departmental circular must operate consistently with the statutory refund formula and cannot require deduction of every reversal reported during the period, thereby curtailing a statutory refund entitlement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915