Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
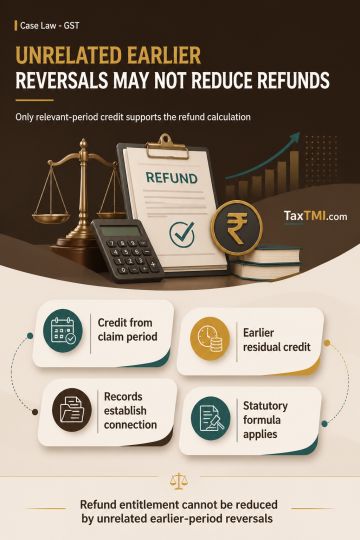
Net ITC for refund of unutilised Compensation Cess credit on zero-rated supplies is confined to input tax credit actually availed and attributable to the relevant refund period. A reversal recorded in that period need not reduce Net ITC where records establish that it relates to residual unutilised credit from earlier tax periods and was not included in the credit supporting the refund claim. Paragraph 43(c) of the departmental circular must operate consistently with the statutory refund formula and cannot require deduction of every reversal reported during the period, thereby curtailing a statutory refund entitlement.
Net ITC for refund of unutilised Compensation Cess credit on zero-rated supplies is confined to input tax credit actually availed and attributable to the relevant refund period. A reversal recorded in that period need not reduce Net ITC where records establish that it relates to residual unutilised credit from earlier tax periods and was not included in the credit supporting the refund claim. Paragraph 43(c) of the departmental circular must operate consistently with the statutory refund formula and cannot require deduction of every reversal reported during the period, thereby curtailing a statutory refund entitlement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918