Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
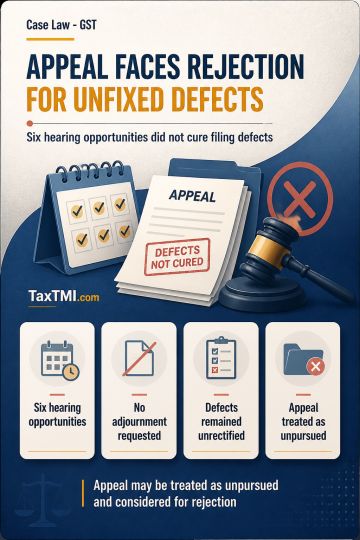
Rule 24(4) of the GSTAT (Procedure) Rules, 2025 permits rejection of an appeal where filing defects remain unrectified despite adequate opportunities. The appellant received six hearing opportunities, including three before the Bench and three before the Registrar, but neither appeared nor sought adjournment. No additional material was uploaded to cure the notified defects. Persistent non-attendance and failure to rectify defects support treating the appeal as not being actively pursued and considering rejection under the procedural rule.
Rule 24(4) of the GSTAT (Procedure) Rules, 2025 permits rejection of an appeal where filing defects remain unrectified despite adequate opportunities. The appellant received six hearing opportunities, including three before the Bench and three before the Registrar, but neither appeared nor sought adjournment. No additional material was uploaded to cure the notified defects. Persistent non-attendance and failure to rectify defects support treating the appeal as not being actively pursued and considering rejection under the procedural rule.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913