Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
Page of 4916
Press 'Enter' after typing page number.
1121 to 1140 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
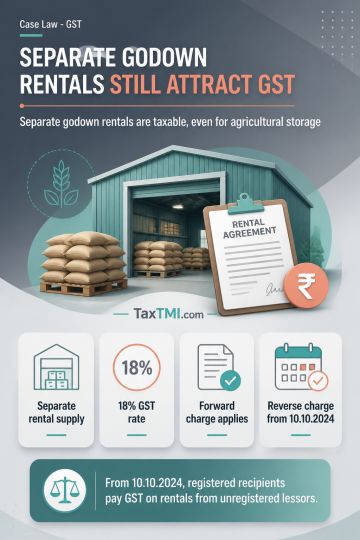
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916