Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
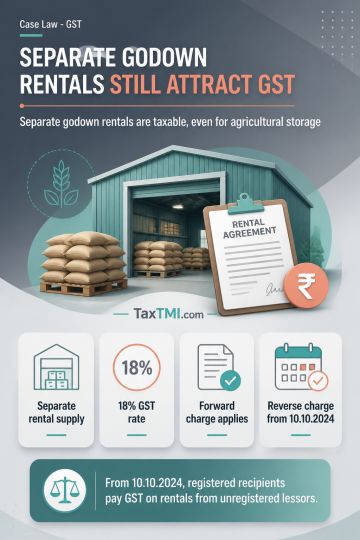
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912