TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
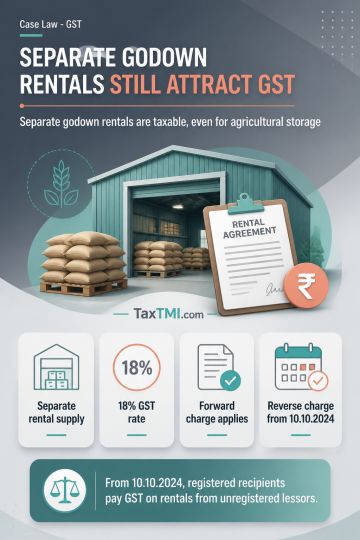
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918