Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
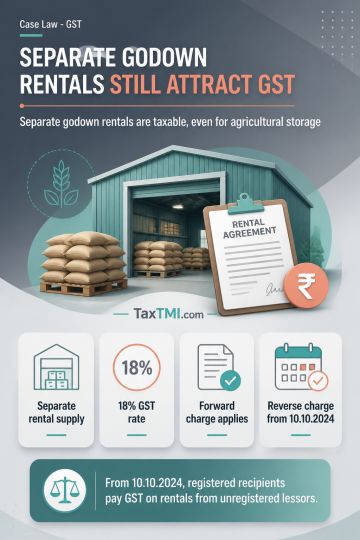
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Storage and warehousing of agricultural produce is exempt, but that exemption does not extend to separately hired godowns used exclusively for the exempt outward service. Renting such godowns constitutes an independent supply of rental or leasing of non-residential property and attracts GST at 18%. Where the lessor is registered, tax is payable under forward charge. Where an unregistered person rents a godown to a registered recipient, the amended reverse-charge entry applies, making the recipient liable to pay GST at 18% from 10.10.2024.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912