Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
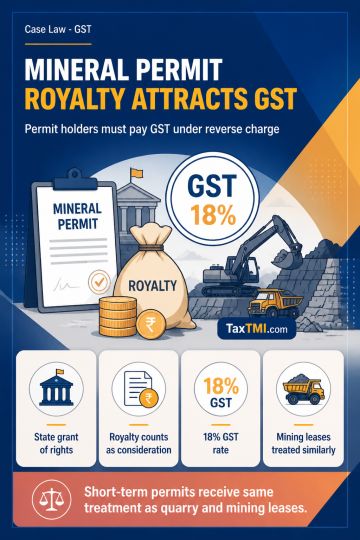
Royalty payable for a State Government grant of mineral extraction rights under a Short-Term Permit is contractual consideration for licensing services involving the right to use minerals, rather than a tax. The permit holder, as recipient of a Government-to-business supply, must discharge GST under reverse charge at 18%. The shorter duration and restricted area of a Short-Term Permit do not change the nature of the supply where the grantor, extraction rights and royalty basis correspond to those for quarry and mining leases. Short-Term Permit holders therefore receive the same reverse-charge GST treatment as quarry and mining lease holders.
Royalty payable for a State Government grant of mineral extraction rights under a Short-Term Permit is contractual consideration for licensing services involving the right to use minerals, rather than a tax. The permit holder, as recipient of a Government-to-business supply, must discharge GST under reverse charge at 18%. The shorter duration and restricted area of a Short-Term Permit do not change the nature of the supply where the grantor, extraction rights and royalty basis correspond to those for quarry and mining leases. Short-Term Permit holders therefore receive the same reverse-charge GST treatment as quarry and mining lease holders.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912