Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
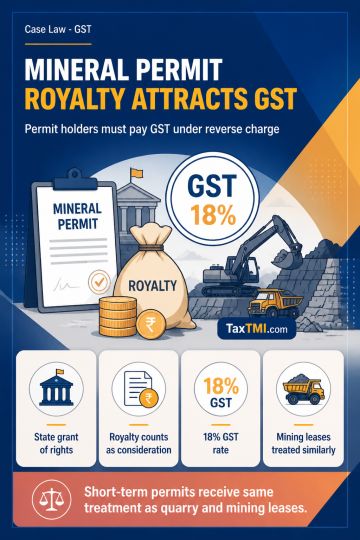
Royalty payable for a State Government grant of mineral extraction rights under a Short-Term Permit is contractual consideration for licensing services involving the right to use minerals, rather than a tax. The permit holder, as recipient of a Government-to-business supply, must discharge GST under reverse charge at 18%. The shorter duration and restricted area of a Short-Term Permit do not change the nature of the supply where the grantor, extraction rights and royalty basis correspond to those for quarry and mining leases. Short-Term Permit holders therefore receive the same reverse-charge GST treatment as quarry and mining lease holders.
Royalty payable for a State Government grant of mineral extraction rights under a Short-Term Permit is contractual consideration for licensing services involving the right to use minerals, rather than a tax. The permit holder, as recipient of a Government-to-business supply, must discharge GST under reverse charge at 18%. The shorter duration and restricted area of a Short-Term Permit do not change the nature of the supply where the grantor, extraction rights and royalty basis correspond to those for quarry and mining leases. Short-Term Permit holders therefore receive the same reverse-charge GST treatment as quarry and mining lease holders.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912