Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
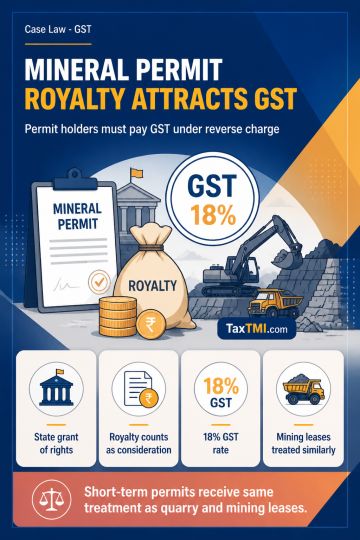
Royalty payable for a State Government grant of mineral extraction rights under a Short-Term Permit is contractual consideration for licensing services involving the right to use minerals, rather than a tax. The permit holder, as recipient of a Government-to-business supply, must discharge GST under reverse charge at 18%. The shorter duration and restricted area of a Short-Term Permit do not change the nature of the supply where the grantor, extraction rights and royalty basis correspond to those for quarry and mining leases. Short-Term Permit holders therefore receive the same reverse-charge GST treatment as quarry and mining lease holders.
Royalty payable for a State Government grant of mineral extraction rights under a Short-Term Permit is contractual consideration for licensing services involving the right to use minerals, rather than a tax. The permit holder, as recipient of a Government-to-business supply, must discharge GST under reverse charge at 18%. The shorter duration and restricted area of a Short-Term Permit do not change the nature of the supply where the grantor, extraction rights and royalty basis correspond to those for quarry and mining leases. Short-Term Permit holders therefore receive the same reverse-charge GST treatment as quarry and mining lease holders.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI