Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
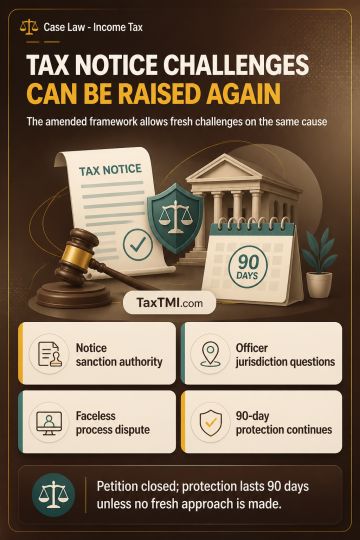
Reassessment litigation concerns the authority to sanction notices, the jurisdiction of a Jurisdictional Assessing Officer to issue them, and whether the prescribed faceless mechanism requires issuance by a competent Faceless Assessment Officer. The 2021 amendments to sections 147 to 151, including new section 147A, may affect pending challenges. Following remand of related matters, the petition was closed with liberty to bring a fresh challenge on the same cause, challenge section 147A, and seek consequential relief. Existing protection continues for 90 days and ceases if no fresh approach is made within that period.
Reassessment litigation concerns the authority to sanction notices, the jurisdiction of a Jurisdictional Assessing Officer to issue them, and whether the prescribed faceless mechanism requires issuance by a competent Faceless Assessment Officer. The 2021 amendments to sections 147 to 151, including new section 147A, may affect pending challenges. Following remand of related matters, the petition was closed with liberty to bring a fresh challenge on the same cause, challenge section 147A, and seek consequential relief. Existing protection continues for 90 days and ceases if no fresh approach is made within that period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915