Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
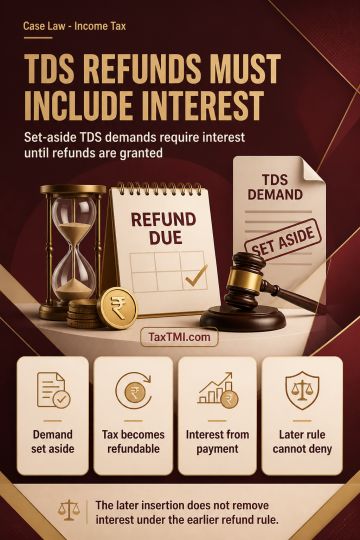
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912