Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
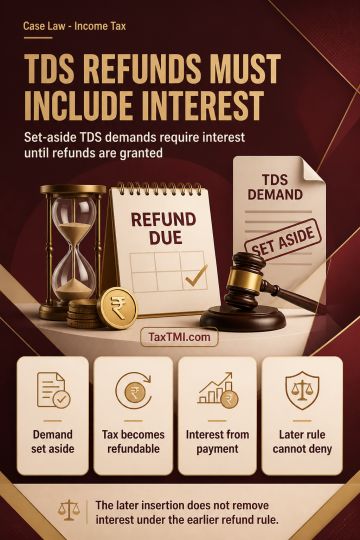
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912