Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
Page of 4918
Press 'Enter' after typing page number.
601 to 620 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
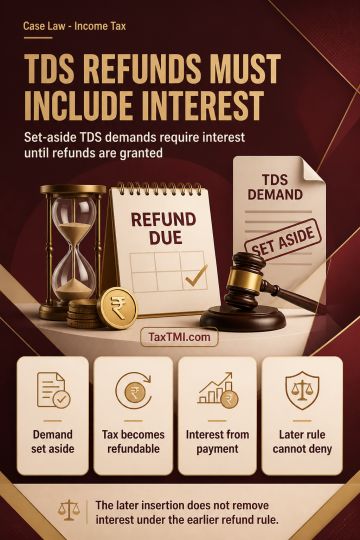
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918