Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
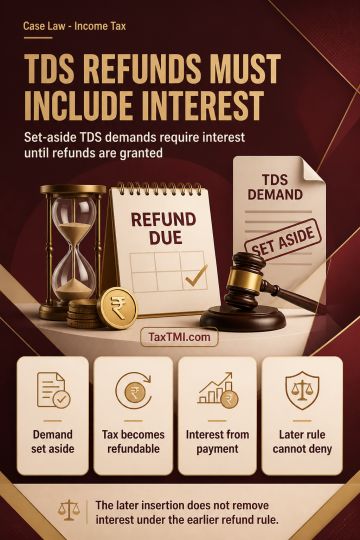
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Interest on refunds of tax paid under a TDS-default demand is governed by Section 244A(1)(b) where the demand is set aside and the tax becomes refundable. That provision covers refunds not specifically falling within Section 244A(1)(a) and requires interest from the date of tax payment until the refund is granted. Section 244A(1B), inserted subsequently, does not deny interest otherwise payable under the pre-existing provision. Revenue retention of money without legal entitlement carries a corresponding obligation to refund the amount with statutory interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915