Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
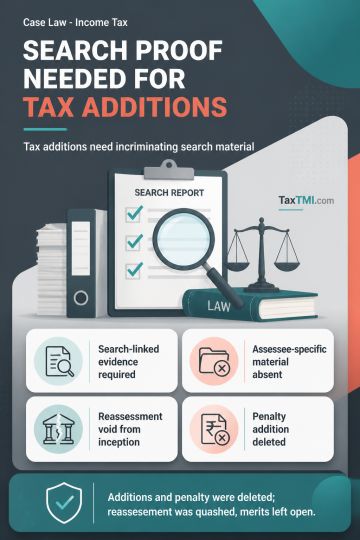
Unabated assessments under section 153A permit additions for escaped income only where incriminating material is found during the search. In the absence of such assessee-specific material, the additions were deleted. Reassessment initiated on recorded reasons that misstated the assessee's investment and conflicted with the investee company's financial statements reflected non-application of mind; the reassessment was therefore void from inception and quashed, with merits left open. Penalty under section 271(1)(c) could not survive once its sole supporting quantum addition had been deleted, and was consequently deleted.
Unabated assessments under section 153A permit additions for escaped income only where incriminating material is found during the search. In the absence of such assessee-specific material, the additions were deleted. Reassessment initiated on recorded reasons that misstated the assessee's investment and conflicted with the investee company's financial statements reflected non-application of mind; the reassessment was therefore void from inception and quashed, with merits left open. Penalty under section 271(1)(c) could not survive once its sole supporting quantum addition had been deleted, and was consequently deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913