Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
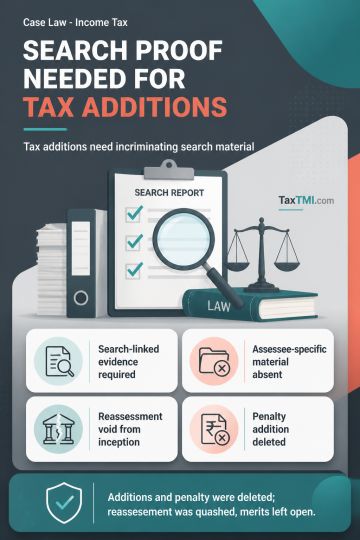
Unabated assessments under section 153A permit additions for escaped income only where incriminating material is found during the search. In the absence of such assessee-specific material, the additions were deleted. Reassessment initiated on recorded reasons that misstated the assessee's investment and conflicted with the investee company's financial statements reflected non-application of mind; the reassessment was therefore void from inception and quashed, with merits left open. Penalty under section 271(1)(c) could not survive once its sole supporting quantum addition had been deleted, and was consequently deleted.
Unabated assessments under section 153A permit additions for escaped income only where incriminating material is found during the search. In the absence of such assessee-specific material, the additions were deleted. Reassessment initiated on recorded reasons that misstated the assessee's investment and conflicted with the investee company's financial statements reflected non-application of mind; the reassessment was therefore void from inception and quashed, with merits left open. Penalty under section 271(1)(c) could not survive once its sole supporting quantum addition had been deleted, and was consequently deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913