Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
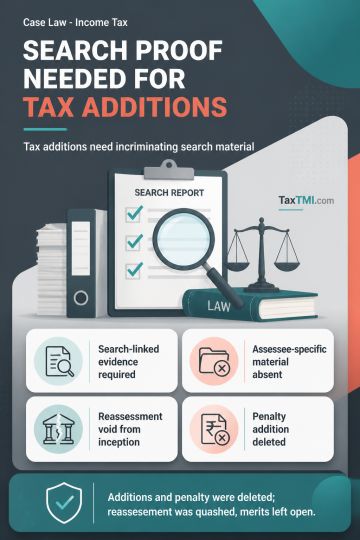
Unabated assessments under section 153A permit additions for escaped income only where incriminating material is found during the search. In the absence of such assessee-specific material, the additions were deleted. Reassessment initiated on recorded reasons that misstated the assessee's investment and conflicted with the investee company's financial statements reflected non-application of mind; the reassessment was therefore void from inception and quashed, with merits left open. Penalty under section 271(1)(c) could not survive once its sole supporting quantum addition had been deleted, and was consequently deleted.
Unabated assessments under section 153A permit additions for escaped income only where incriminating material is found during the search. In the absence of such assessee-specific material, the additions were deleted. Reassessment initiated on recorded reasons that misstated the assessee's investment and conflicted with the investee company's financial statements reflected non-application of mind; the reassessment was therefore void from inception and quashed, with merits left open. Penalty under section 271(1)(c) could not survive once its sole supporting quantum addition had been deleted, and was consequently deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912