Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
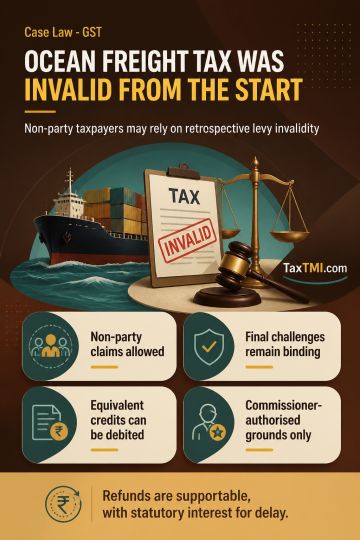
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Page of 4915
Press 'Enter' after typing page number.
481 to 500 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Conversion of a capital asset into stock-in-trade under a joint...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Income.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Conversion of a capital asset into stock-in-trade under a joint development arrangement requires proof that the asset entered the assessee's business stock; executing such an arrangement alone, particularly without a real-estate business, does not establish conversion. On that basis, the long-term capital-gains addition was deleted. A transfer of flats to a spouse without actual consideration, made to safeguard property interests, is not a sale merely because a sale deed records consideration. The deed recital cannot establish income received, and the business-income addition was deleted.
Conversion of a capital asset into stock-in-trade under a joint development arrangement requires proof that the asset entered the assessee's business stock; executing such an arrangement alone, particularly without a real-estate business, does not establish conversion. On that basis, the long-term capital-gains addition was deleted. A transfer of flats to a spouse without actual consideration, made to safeguard property interests, is not a sale merely because a sale deed records consideration. The deed recital cannot establish income received, and the business-income addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915