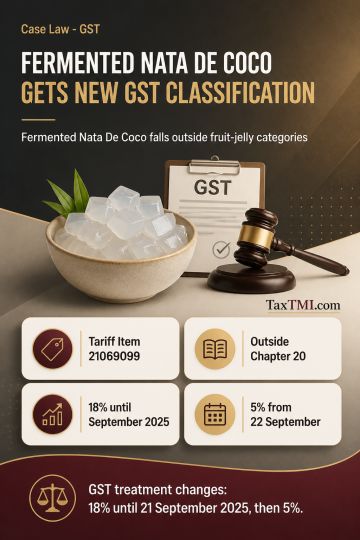
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Tax deduction at source on interest arises on credit or payment, whichever occurs first; a brought-forward interest liability does not itself constitute a current-year credit. The real income doctrine requires objectively established contemporaneous circumstances showing that income did not accrue, rather than merely an absence of accounting entries. Unexplained-expenditure provisions apply to expenditure incurred in the relevant financial year and do not extend to an earlier capital advance merely carried forward, particularly where recorded in regular books. A capital work-in-progress write-off already added back in computing business income should not be added again, as this would result in double taxation. Interest capitalised to work-in-progress is not subject to disallowance where tax was deducted and deposited within the prescribed return-filing timeline.
Tax deduction at source on interest arises on credit or payment, whichever occurs first; a brought-forward interest liability does not itself constitute a current-year credit. The real income doctrine requires objectively established contemporaneous circumstances showing that income did not accrue, rather than merely an absence of accounting entries. Unexplained-expenditure provisions apply to expenditure incurred in the relevant financial year and do not extend to an earlier capital advance merely carried forward, particularly where recorded in regular books. A capital work-in-progress write-off already added back in computing business income should not be added again, as this would result in double taxation. Interest capitalised to work-in-progress is not subject to disallowance where tax was deducted and deposited within the prescribed return-filing timeline.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916