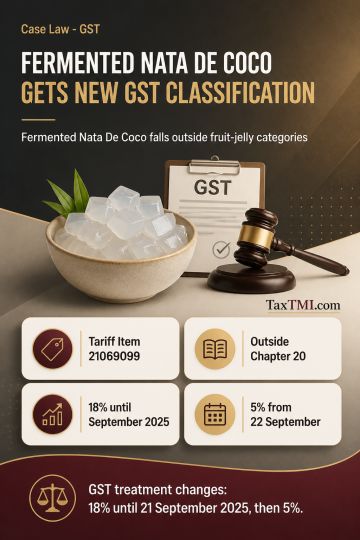
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Page of 4920
Press 'Enter' after typing page number.
1201 to 1220 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 50B prescribes a self-contained method for computing capital gains on a slump sale, including fair market value and net worth under Rule 11UAE. Where no defect in the valuation methodology or non-compliance with Rule 11UAE is identified, the Assessing Officer cannot substitute a different valuation; deletion of the resulting capital-gains addition was confirmed. A capital-gains addition made without a proper show-cause notice also breached CBDT Instruction No. 20/2015 and was independently unsustainable. The Revenue's appeal was dismissed.
Section 50B prescribes a self-contained method for computing capital gains on a slump sale, including fair market value and net worth under Rule 11UAE. Where no defect in the valuation methodology or non-compliance with Rule 11UAE is identified, the Assessing Officer cannot substitute a different valuation; deletion of the resulting capital-gains addition was confirmed. A capital-gains addition made without a proper show-cause notice also breached CBDT Instruction No. 20/2015 and was independently unsustainable. The Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920