Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Page of 4921
Press 'Enter' after typing page number.
601 to 620 of 98414 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
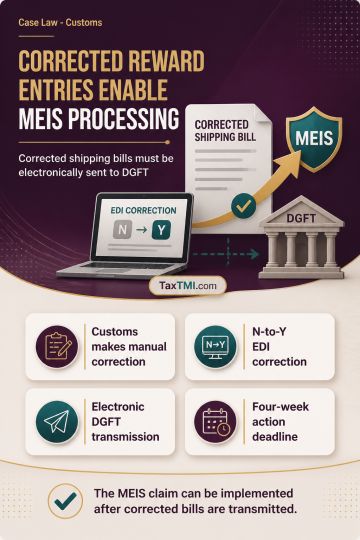
MEIS benefit processing requires a shipping bill's Reward declaration, inadvertently entered as 'N', to be corrected to 'Y' in the EDI system after Customs has made the corresponding manual correction. The amended shipping bills must then be electronically transmitted to DGFT under the prescribed public-notice procedure so that the MEIS claim can be implemented. Administrative technology must facilitate, rather than obstruct, a rectifiable procedural correction; the specified Customs and DGFT actions are to be completed within four weeks of communication.
MEIS benefit processing requires a shipping bill's Reward declaration, inadvertently entered as 'N', to be corrected to 'Y' in the EDI system after Customs has made the corresponding manual correction. The amended shipping bills must then be electronically transmitted to DGFT under the prescribed public-notice procedure so that the MEIS claim can be implemented. Administrative technology must facilitate, rather than obstruct, a rectifiable procedural correction; the specified Customs and DGFT actions are to be completed within four weeks of communication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921