Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
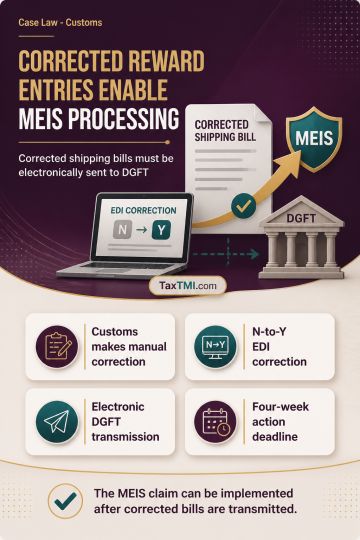
MEIS benefit processing requires a shipping bill's Reward declaration, inadvertently entered as 'N', to be corrected to 'Y' in the EDI system after Customs has made the corresponding manual correction. The amended shipping bills must then be electronically transmitted to DGFT under the prescribed public-notice procedure so that the MEIS claim can be implemented. Administrative technology must facilitate, rather than obstruct, a rectifiable procedural correction; the specified Customs and DGFT actions are to be completed within four weeks of communication.
MEIS benefit processing requires a shipping bill's Reward declaration, inadvertently entered as 'N', to be corrected to 'Y' in the EDI system after Customs has made the corresponding manual correction. The amended shipping bills must then be electronically transmitted to DGFT under the prescribed public-notice procedure so that the MEIS claim can be implemented. Administrative technology must facilitate, rather than obstruct, a rectifiable procedural correction; the specified Customs and DGFT actions are to be completed within four weeks of communication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916