Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
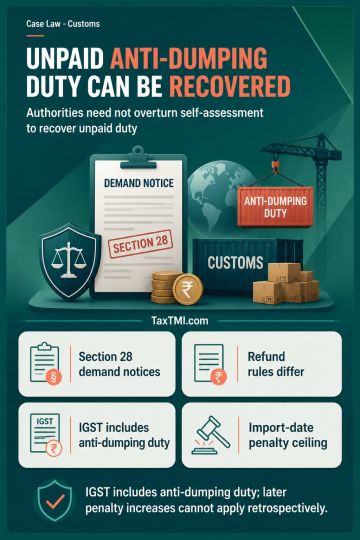
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915