Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
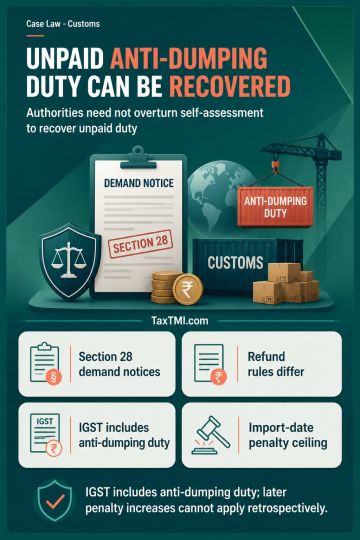
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915