Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Page of 4915
Press 'Enter' after typing page number.
581 to 600 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
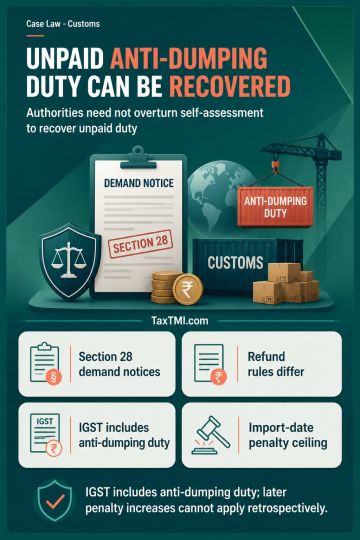
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915