Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
Page of 4918
Press 'Enter' after typing page number.
361 to 380 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
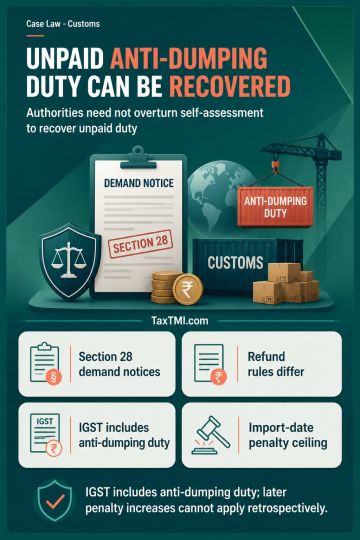
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Section 28 permits recovery of unpaid or short-paid anti-dumping duty through a demand notice without first challenging the importer's self-assessment. This recovery mechanism is distinct from refund proceedings, where an unmodified self-assessment may restrict relief. Anti-dumping duty imposed under the Customs Tariff Act is treated as customs duty for calculating IGST on imported goods; IGST therefore applies to the aggregate value including such duty. The maximum penalty for non-payment is governed by the statutory ceiling applicable on the date of import, and a subsequently enhanced ceiling cannot apply retrospectively.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918