Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Amounts deposited during customs investigation under protest...
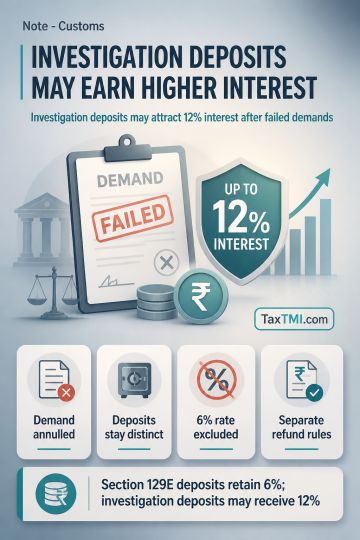
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensatory interest.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Amounts deposited during customs investigation under protest retain their character as investigation deposits when the related duty demand is annulled, despite later appropriation. They are distinct from statutory appellate deposits under Section 129E; consequently, Section 129EE's notified 6% interest rate does not govern them. Where no statutory rate applies, entitlement to restitutionary interest depends on applicable binding judicial precedent. Jurisdictional precedent supported 12% interest on the refundable investigation deposit, while confining the 6% rate to amounts actually deposited under Section 129E. Section 27's protest exception and Section 27A's delayed-refund framework require separate assessment according to the payment's legal character.
Amounts deposited during customs investigation under protest retain their character as investigation deposits when the related duty demand is annulled, despite later appropriation. They are distinct from statutory appellate deposits under Section 129E; consequently, Section 129EE's notified 6% interest rate does not govern them. Where no statutory rate applies, entitlement to restitutionary interest depends on applicable binding judicial precedent. Jurisdictional precedent supported 12% interest on the refundable investigation deposit, while confining the 6% rate to amounts actually deposited under Section 129E. Section 27's protest exception and Section 27A's delayed-refund framework require separate assessment according to the payment's legal character.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921