Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Amounts deposited during customs investigation under protest...
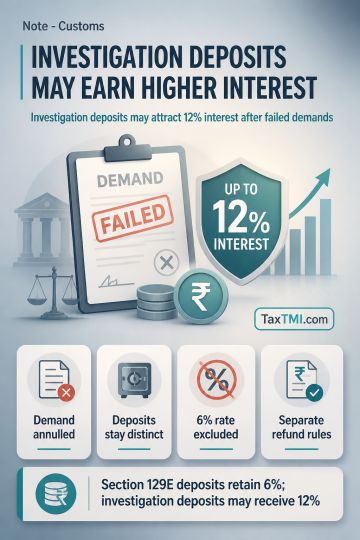
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensatory interest.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Amounts deposited during customs investigation under protest retain their character as investigation deposits when the related duty demand is annulled, despite later appropriation. They are distinct from statutory appellate deposits under Section 129E; consequently, Section 129EE's notified 6% interest rate does not govern them. Where no statutory rate applies, entitlement to restitutionary interest depends on applicable binding judicial precedent. Jurisdictional precedent supported 12% interest on the refundable investigation deposit, while confining the 6% rate to amounts actually deposited under Section 129E. Section 27's protest exception and Section 27A's delayed-refund framework require separate assessment according to the payment's legal character.
Amounts deposited during customs investigation under protest retain their character as investigation deposits when the related duty demand is annulled, despite later appropriation. They are distinct from statutory appellate deposits under Section 129E; consequently, Section 129EE's notified 6% interest rate does not govern them. Where no statutory rate applies, entitlement to restitutionary interest depends on applicable binding judicial precedent. Jurisdictional precedent supported 12% interest on the refundable investigation deposit, while confining the 6% rate to amounts actually deposited under Section 129E. Section 27's protest exception and Section 27A's delayed-refund framework require separate assessment according to the payment's legal character.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915