Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
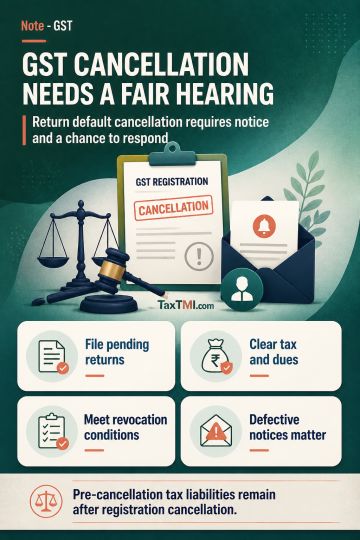
GST registration may be cancelled for continuous non-filing of returns under Section 29, but cancellation does not extinguish pre-cancellation tax liabilities. Rule 22 requires notice and an opportunity to respond; where pending returns are filed and tax, interest and late fee are fully paid before cancellation, the officer must drop proceedings. Post-cancellation revocation under Rule 23 requires compliance with prescribed filing, payment and limitation conditions, while appellate authorities cannot exceed statutory condonation limits. Defective notices, absence of reasons, denial of meaningful hearing, or unexplained retrospective cancellation may invalidate the process. Conditional restoration may be available in appropriate non-fraud cases upon full regularisation of returns, tax, interest, late fee and penalty.
GST registration may be cancelled for continuous non-filing of returns under Section 29, but cancellation does not extinguish pre-cancellation tax liabilities. Rule 22 requires notice and an opportunity to respond; where pending returns are filed and tax, interest and late fee are fully paid before cancellation, the officer must drop proceedings. Post-cancellation revocation under Rule 23 requires compliance with prescribed filing, payment and limitation conditions, while appellate authorities cannot exceed statutory condonation limits. Defective notices, absence of reasons, denial of meaningful hearing, or unexplained retrospective cancellation may invalidate the process. Conditional restoration may be available in appropriate non-fraud cases upon full regularisation of returns, tax, interest, late fee and penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915