Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
Page of 4913
Press 'Enter' after typing page number.
1101 to 1120 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
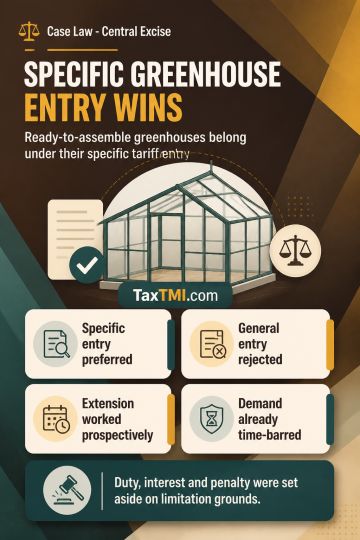
Greenhouses cleared from the factory in ready-to-assemble condition fall under the specific tariff entry for greenhouses in ready-to-assemble sets rather than the general entry for plant growth chambers, applying Rule 3(a)'s preference for the most specific description. An amendment extending the normal excise-demand limitation period from one year to two years operates prospectively absent express retrospective effect and cannot revive a demand already time-barred. On that limitation basis, the duty demand, interest and penalty were set aside.
Greenhouses cleared from the factory in ready-to-assemble condition fall under the specific tariff entry for greenhouses in ready-to-assemble sets rather than the general entry for plant growth chambers, applying Rule 3(a)'s preference for the most specific description. An amendment extending the normal excise-demand limitation period from one year to two years operates prospectively absent express retrospective effect and cannot revive a demand already time-barred. On that limitation basis, the duty demand, interest and penalty were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913