Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Page of 4918
Press 'Enter' after typing page number.
661 to 680 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
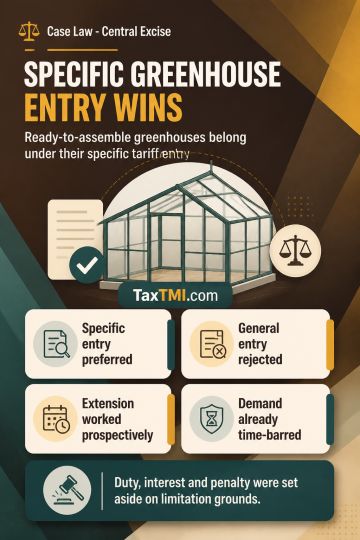
Greenhouses cleared from the factory in ready-to-assemble condition fall under the specific tariff entry for greenhouses in ready-to-assemble sets rather than the general entry for plant growth chambers, applying Rule 3(a)'s preference for the most specific description. An amendment extending the normal excise-demand limitation period from one year to two years operates prospectively absent express retrospective effect and cannot revive a demand already time-barred. On that limitation basis, the duty demand, interest and penalty were set aside.
Greenhouses cleared from the factory in ready-to-assemble condition fall under the specific tariff entry for greenhouses in ready-to-assemble sets rather than the general entry for plant growth chambers, applying Rule 3(a)'s preference for the most specific description. An amendment extending the normal excise-demand limitation period from one year to two years operates prospectively absent express retrospective effect and cannot revive a demand already time-barred. On that limitation basis, the duty demand, interest and penalty were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918