Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
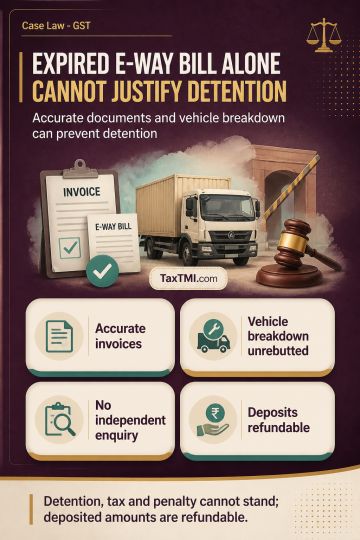
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912