Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
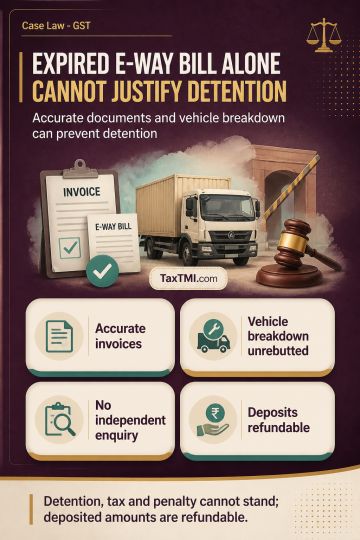
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912