Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
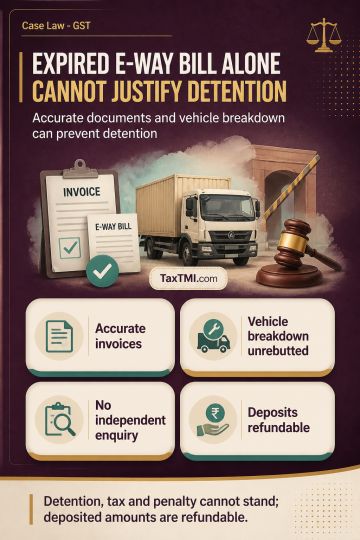
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912