Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Page of 4921
Press 'Enter' after typing page number.
701 to 720 of 98407 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
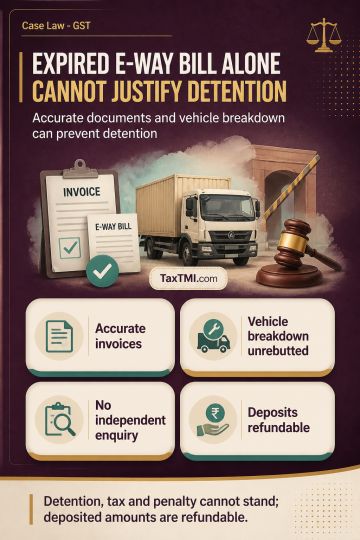
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Section 129(3) detention and penalty provisions should not be applied solely because an e-way bill has expired where invoices and transport documents are accurate. An unrebutted vehicle breakdown, coupled with no independent enquiry, does not support an adverse inference that goods were moved to evade tax. In these circumstances, expiry alone does not establish intent to evade tax, and detention, consequential tax and penalty cannot be sustained; deposited amounts are refundable in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921