Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Page of 4920
Press 'Enter' after typing page number.
1121 to 1140 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
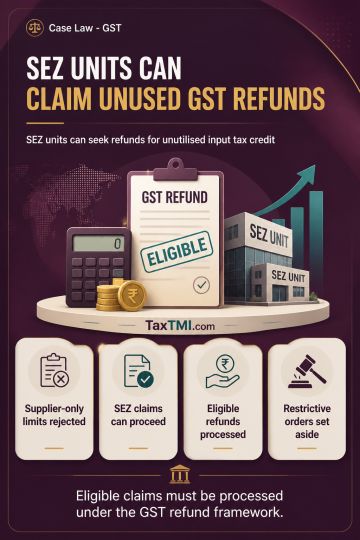
GST refund provisions for unutilised input tax credit do not restrict refund applications to suppliers making supplies to SEZ units. The relevant refund rule identifies suppliers as one category of applicants but does not exclude an SEZ unit from claiming its own refund. Reading such a restriction into the statutory scheme would impermissibly add a limiting condition. SEZ units are therefore entitled to have eligible refund claims processed under the GST refund framework, and orders rejecting the claim on that restrictive basis were set aside.
GST refund provisions for unutilised input tax credit do not restrict refund applications to suppliers making supplies to SEZ units. The relevant refund rule identifies suppliers as one category of applicants but does not exclude an SEZ unit from claiming its own refund. Reading such a restriction into the statutory scheme would impermissibly add a limiting condition. SEZ units are therefore entitled to have eligible refund claims processed under the GST refund framework, and orders rejecting the claim on that restrictive basis were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920