Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
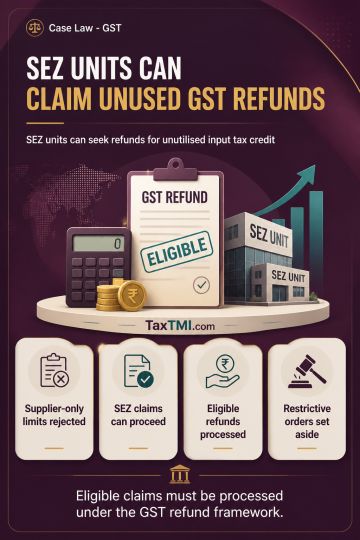
GST refund provisions for unutilised input tax credit do not restrict refund applications to suppliers making supplies to SEZ units. The relevant refund rule identifies suppliers as one category of applicants but does not exclude an SEZ unit from claiming its own refund. Reading such a restriction into the statutory scheme would impermissibly add a limiting condition. SEZ units are therefore entitled to have eligible refund claims processed under the GST refund framework, and orders rejecting the claim on that restrictive basis were set aside.
GST refund provisions for unutilised input tax credit do not restrict refund applications to suppliers making supplies to SEZ units. The relevant refund rule identifies suppliers as one category of applicants but does not exclude an SEZ unit from claiming its own refund. Reading such a restriction into the statutory scheme would impermissibly add a limiting condition. SEZ units are therefore entitled to have eligible refund claims processed under the GST refund framework, and orders rejecting the claim on that restrictive basis were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915