Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
Tariff classification of Digital Axle Counters affirmed as electro-mechanical railway signalling equipment, eliminating duty, confiscation and penalty...
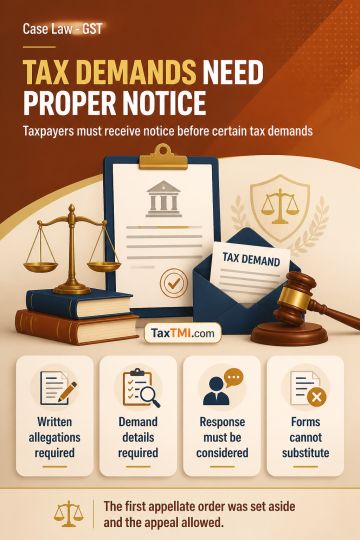
Section 74 tax determinations based on suppression of facts require service of a statutory show cause notice and consideration of the taxpayer's representation. The notice must specify the demand, foundational facts and necessary particulars so the taxpayer can respond effectively. GST DRC forms or other communications cannot substitute for the statutory notice. Determining a demand without serving such notice denies the taxpayer knowledge of the allegations and an effective opportunity of representation, vitiating the proceedings; the first appellate order was set aside and the appeal allowed.
Section 74 tax determinations based on suppression of facts require service of a statutory show cause notice and consideration of the taxpayer's representation. The notice must specify the demand, foundational facts and necessary particulars so the taxpayer can respond effectively. GST DRC forms or other communications cannot substitute for the statutory notice. Determining a demand without serving such notice denies the taxpayer knowledge of the allegations and an effective opportunity of representation, vitiating the proceedings; the first appellate order was set aside and the appeal allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913