Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
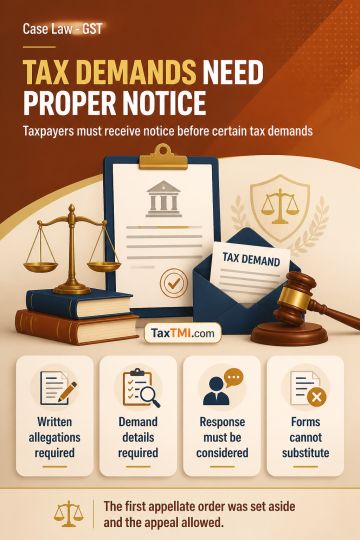
Section 74 tax determinations based on suppression of facts require service of a statutory show cause notice and consideration of the taxpayer's representation. The notice must specify the demand, foundational facts and necessary particulars so the taxpayer can respond effectively. GST DRC forms or other communications cannot substitute for the statutory notice. Determining a demand without serving such notice denies the taxpayer knowledge of the allegations and an effective opportunity of representation, vitiating the proceedings; the first appellate order was set aside and the appeal allowed.
Section 74 tax determinations based on suppression of facts require service of a statutory show cause notice and consideration of the taxpayer's representation. The notice must specify the demand, foundational facts and necessary particulars so the taxpayer can respond effectively. GST DRC forms or other communications cannot substitute for the statutory notice. Determining a demand without serving such notice denies the taxpayer knowledge of the allegations and an effective opportunity of representation, vitiating the proceedings; the first appellate order was set aside and the appeal allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915