Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
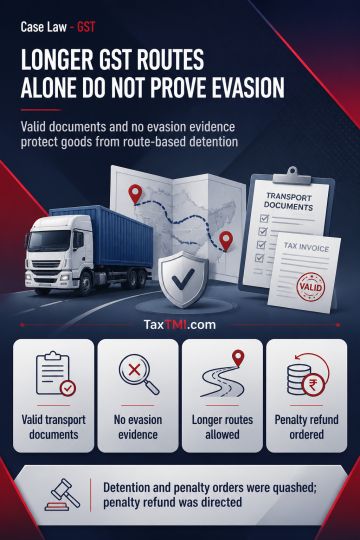
GST law does not require a transporter to declare or follow a particular route. Transporting goods by a longer route for logistical safety reasons, while carrying valid documents, does not establish mala fide intent to evade tax without material showing an intended diversion or other tax evasion. Route-based obligations under earlier VAT regimes do not apply under the GST Acts or Rules. Accordingly, detention of goods and penalty under section 129 were unsustainable solely because a longer route was used; the detention-penalty orders were quashed and refund of the penalty paid under protest was directed in accordance with law.
GST law does not require a transporter to declare or follow a particular route. Transporting goods by a longer route for logistical safety reasons, while carrying valid documents, does not establish mala fide intent to evade tax without material showing an intended diversion or other tax evasion. Route-based obligations under earlier VAT regimes do not apply under the GST Acts or Rules. Accordingly, detention of goods and penalty under section 129 were unsustainable solely because a longer route was used; the detention-penalty orders were quashed and refund of the penalty paid under protest was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915